Learn how medical billing and claims work, how coordination of benefits handles multiple insurance plans, and what the Birthday Rule means for your behavioral health practice.
If you run a therapy or counseling practice, you know the clinical side well. The billing side is where many practices lose time and revenue. A patient arrives with two insurance cards, the claim goes to the wrong payer, and weeks later a denial comes back.
This guide explains how medical billing and claims work for behavioral health providers, how coordination of benefits decides which insurance pays first, and how the Birthday Rule applies to children covered by two parents.
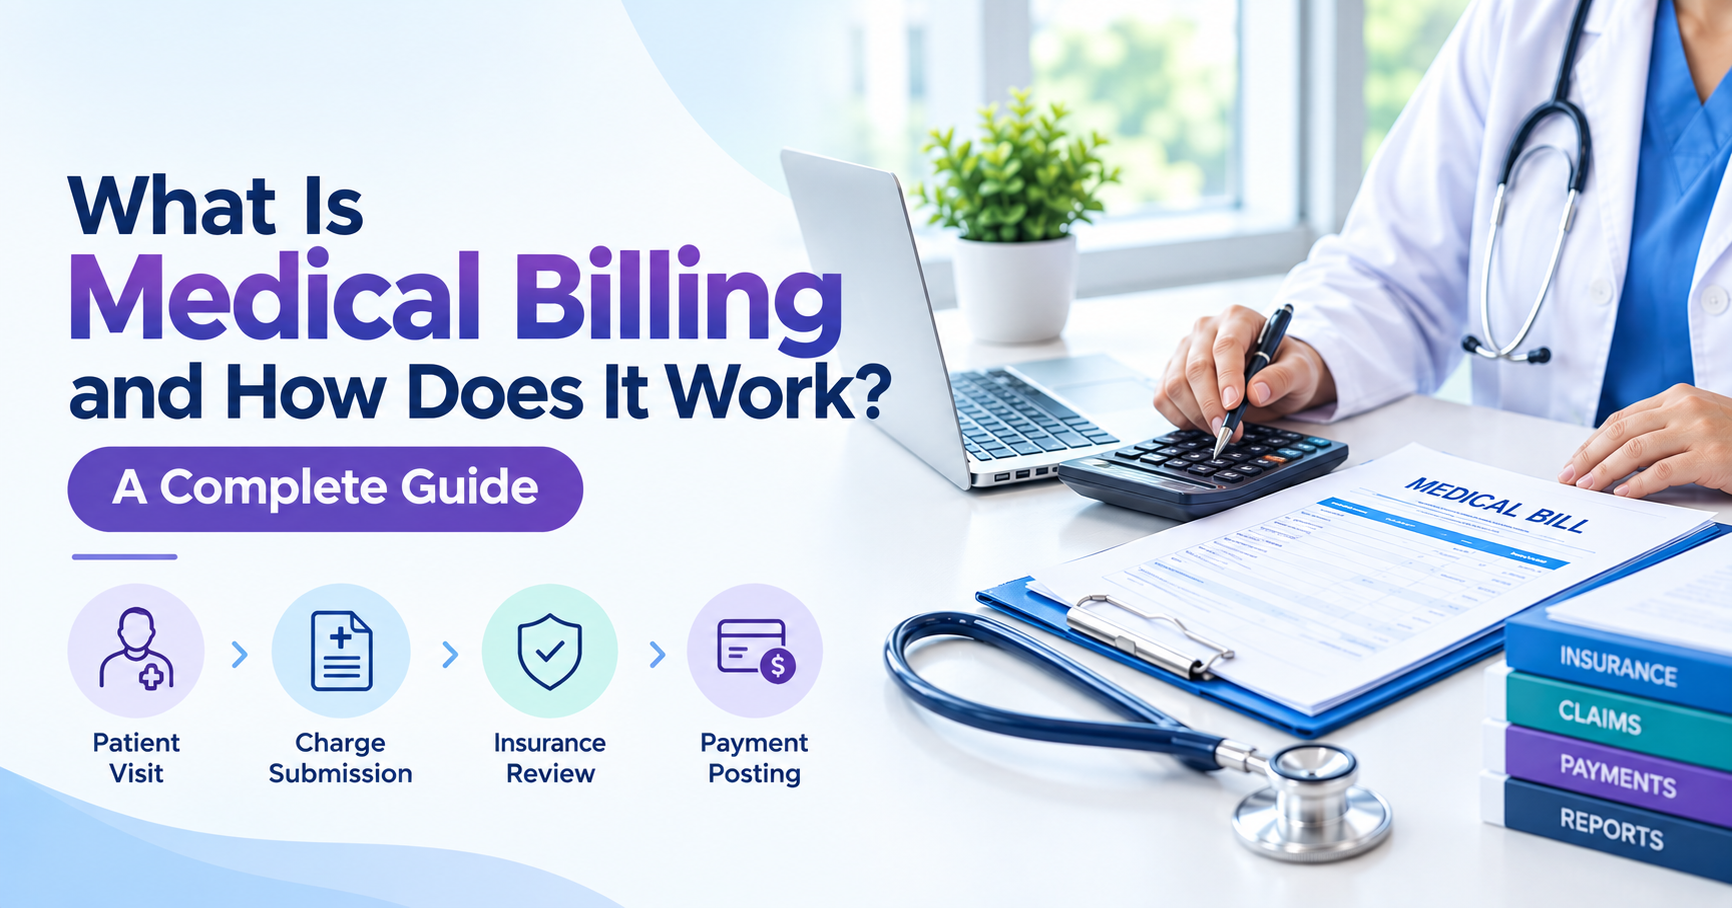
How Medical Billing and Claims Work: The Basic Flow
Medical billing is the process of turning a patient visit into payment from the insurance company. For a behavioral health provider such as an LCSW, psychologist, or psychiatrist, it usually looks like this:
Patient registration: Collect demographics and a copy of the front and back of every insurance card.
Insurance verification: Confirm the patient's coverage is active, check mental health benefits, copay, deductible, session limits, and whether prior authorization is needed.
Service and documentation: The provider delivers the session and completes a clinical note that supports medical necessity.
Coding: The visit is coded with the right CPT and ICD-10 codes. Common behavioral health codes include 90791 (diagnostic evaluation), 90834 (45-minute psychotherapy) and 90837 (60-minute psychotherapy).
Claim submission: The claim is sent electronically (837P) or on a CMS-1500 form to the payer, usually through a clearinghouse.
Payer adjudication: The insurer reviews the claim and pays, adjusts, or denies it.
Payment posting and follow-up: The payment and remittance advice (ERA/EOB) are posted. Any denied or underpaid claim is followed up or appealed.
Patient billing: Any remaining copay, coinsurance, or deductible is billed to the patient.
A mistake at any step, such as a wrong member ID, missing authorization, or incorrect code, can delay or deny the claim. That is why many practices turn to professional healthcare billing services.
What If the Patient Has Multiple Insurance Plans?
It is very common for a patient to have multiple insurance plans. For example:
A patient has their own employer plan and also a spouse's plan.
A patient has Medicare plus a supplemental or employer plan.
A child is covered under both parents' plans.
A patient has Medicaid in addition to a private plan.
When this happens, the plans must decide who pays first. This is called coordination of benefits (COB).
Coordination of Benefits (COB): Who Pays First?
COB is the set of rules insurers use to avoid paying more than 100% of a bill and to decide the payment order.
Primary insurance pays first, according to its normal benefits.
Secondary insurance may pay some or all of what remains, depending on its own rules.
General guidelines:
Own employer plan vs. spouse's plan: The patient's own employer plan is usually primary. The spouse's plan is secondary.
Medicare and employer coverage: This depends on factors such as the patient's age, disability status, and the employer's size. For people 65 or older with employer coverage, the employer plan is generally primary if the employer is large enough (typically 20 or more employees). Otherwise Medicare is usually primary.
Medicaid: Medicaid is generally the payer of last resort and pays after other coverage.
Always verify the order with the payer. Rules vary by plan type and situation, and the insurer's records are what count.
What Is the Birthday Rule?
The Birthday Rule decides which parent's plan is primary for a dependent child covered under both parents' plans.
The parent whose birthday falls earlier in the calendar year has the primary plan for the child.
Only the month and day count, not the year of birth.
Example: The mother's birthday is March 10 and the father's is August 22. The mother's plan is primary for the child, and the father's plan is secondary.
Exceptions: For children of separated or divorced parents, the order is usually set by a court order first. If there is none, the custodial parent's plan is typically primary. Always check the specific plan's rules.
How Secondary Insurance Billing Works
Secondary insurance billing follows a clear order:
Submit the claim to the primary insurer first.
Receive the EOB/ERA showing what was allowed, paid, and adjusted.
Submit a claim to the secondary insurer with the primary's payment details attached or included electronically.
The secondary reviews the balance and pays according to its own coverage rules.
Bill the patient only for the remaining responsibility, and only after both payers have processed the claim.
Common mistakes that cause denials:
Billing the wrong insurance as primary
Not updating COB information when a patient's coverage changes
Missing the secondary's timely filing deadline
Sending the secondary claim without the primary's EOB/ERA
Not confirming the provider is in-network with both plans
Why This Matters for Behavioral Health Providers
Behavioral health billing has its own challenges:
Session limits and authorization requirements vary by plan.
Many plans route mental health benefits through a separate behavioral health vendor.
Time-based codes (like 90834 and 90837) must match documentation exactly.
Credentialing must be complete with every payer you bill, or claims will be denied.
Getting COB wrong on top of these issues means delayed payments and lost revenue.
How Professional Medical Billing Services Help
Handling all this in-house takes staff time away from your patients. A dedicated medical billing for providers partner can:
Verify eligibility and COB before the appointment
Submit clean claims to the right payer in the right order
Manage secondary and tertiary billing
Follow up on denials and file appeals
Handle credentialing and prior authorizations
Give you clear reports on your revenue cycle
Why Do Claims With Multiple Insurance Plans Get Denied?
Claims with more than one plan get denied for a short list of predictable reasons, and most trace back to coordination of benefits or the order of billing. Catching these early keeps revenue moving.
Coordination of benefits not on file. The payer needs the patient to confirm they do not have other primary coverage, and the claim is held until they do.
Wrong payer billed first. Filing the secondary plan as primary, or the reverse, triggers a denial.
Missing primary EOB. The secondary claim arrives without proof of what the primary paid.
Timely filing lapse. The secondary claim is filed after its deadline because the primary took too long.
Not enrolled with the payer. The provider is out of network with one of the plans.
Duplicate or overpayment recoupment. Both plans paid as primary, and one asks for its money back.
When these denials pile up, our denial management team finds the root cause and reworks the claims, and our guide to the common reasons medical claims are denied explains what to check first.
Should You Handle Multiple Insurance Billing In House or Outsource It?
In-house billing can handle multiple insurance claims when you have staff with the time to verify coordination of benefits, post EOBs, and follow up on both payers for every claim. It becomes a problem when volume grows, because secondary claims are the first thing a busy team lets slide.
Outsourcing to a medical billing service makes sense when your secondary claims are aging, your coordination of benefits denials are climbing, or your staff cannot keep up with verification and follow up. A billing partner works both payers on every claim and tracks the filing deadlines, so the revenue that in-house teams often lose on secondary claims gets collected.
How Can Avorcms Services Help With Multiple Insurance Billing?
Avorcms Services manages billing for patients with multiple insurance plans, including coordination of benefits verification, primary and secondary claim submission, EOB posting, and follow up on both payers. We treat secondary claims with the same attention as primary claims, so nothing is left uncollected.
Multiple insurance billing is one piece of a larger revenue cycle. We can support your full billing operation through our revenue cycle management services, with a dedicated account manager who knows your practice. Aging primary and secondary balances are worked by our AR recovery specialists, who chase the claims many billing companies give up on. We provide billing across the specialties we serve, including behavioral health, therapy and rehabilitation, family and internal medicine, OB GYN, chiropractic, pediatrics, ophthalmology, and orthopedics.
Stop Losing Revenue on Secondary Claims
Every secondary claim that goes unbilled or gets denied is money your practice already earned. Coordination of benefits does not have to be a source of lost revenue. Let our team verify the coverage, bill both payers in the right order, and follow up until each claim is paid.
👉 Request your free billing audit | [email protected] | Reach the Avorcms Services team
Serving independent practices, group practices, and healthcare providers across the United States.
Frequently Asked Questions
1. What does coordination of benefits mean in medical billing?
Coordination of benefits is the set of rules that decides the order multiple insurance plans pay in, so the combined payment does not exceed the cost of care. It determines which plan is primary and which is secondary.
2. How do you know which insurance is primary and which is secondary?
The primary plan is set by coordination of benefits rules, not patient choice. A patient's own employer plan is usually primary over a plan where they are a dependent, and for children the birthday rule or a court order applies.
3. What is the birthday rule for children with two insurance plans?
When a child is covered under both parents, the plan of the parent whose birthday falls earlier in the calendar year is primary. Only the month and day count, not the birth year.
4. Do you bill primary or secondary insurance first?
You always bill the primary payer first and wait for its explanation of benefits. Then you bill the secondary payer for the remaining balance, including the primary EOB.
5. How long do you have to bill secondary insurance?
Each payer sets its own timely filing deadline, and the clock does not pause while you wait on the primary. File the secondary claim as soon as the primary EOB posts so you do not miss the window.
6. What happens if you bill the wrong insurance as primary?
The claim is usually denied and must be corrected and refiled to the correct primary payer. Billing the wrong payer can also cause overpayments that the plan later recoups.
7. Is Medicare primary or secondary when a patient has other insurance?
It depends on the patient's situation. For a working patient 65 or older with a group plan from an employer of 20 or more, the group plan is primary and Medicare is secondary, while retirees usually have Medicare as primary.
8. Can a patient have three insurance plans?
Yes. When a patient has a tertiary plan, you bill the primary first, then the secondary, then the tertiary, using each payer's EOB to bill the next one.
9. Why did my secondary insurance claim get denied?
The most common reasons are a missing primary EOB, coordination of benefits not on file, the wrong payer billed first, or a missed timely filing deadline. Correcting the order and attaching the primary EOB resolves most of these.
10. Does Avorcms Services handle billing for patients with multiple insurance plans?
Yes. We manage coordination of benefits, primary and secondary claims, EOB posting, and follow up on both payers. You can contact our billing team, call (727) 662 8558, or email [email protected], and we respond within 24 hours.
Disclaimer: This blog is for informational and educational purposes only and does not constitute legal, compliance, or financial advice. Payer requirements and coordination of benefits rules vary, so confirm details with each payer.